Greenwood Archer Capital is a nonprofit 501(c)(3) Community Development Financial Institution that expands access to fair, flexible financing for entrepreneurs in historically underinvested communities.
Our vision
A Chicago where every neighborhood prospers because every entrepreneur has access to the resources they need to succeed. More than lenders, we are trusted partners in revitalization, rooted in relationships and community.
A letter from our Executive Director
Greenwood Archer Capital is entering its next chapter.
Our first years were about proving that there is both a need and an opportunity to build a different kind of community lender, one that combines flexible capital, strong relationships, and meaningful support to help entrepreneurs build sustainable businesses.
A letter from our Board Chair
GAC was created with a clear purpose:
to expand access to capital and opportunity for entrepreneurs and communities that have historically faced barriers to traditional financing. Our vision goes beyond making loans. We believe small businesses can be powerful engines of job creation, neighborhood investment, economic mobility, and generational wealth.
Impact at a glance
Lending has grown every year since FY2024: $1.2 million that year, $2.8 million in FY2025, and $5.6 million in FY2026, doubling in a single year.
FY2026, July 2025 to June 2026
Since 2012
$49KAverage per loan
FY2024
$1.2MLendingloans approved
$69.9KAverage per loan
15Businesses
FY2025
$2.8MLendingloans approved
$70KAverage per loan
32Clients
FY2026
$122KAverage per loan
Lending by fiscal year
New leadership took over halfway through FY2024. Since then, annual lending has grown from $1.2M to $5.6M, about 4.7 times.
Lending by fiscal year: FY2013 $0.2M, FY2014 $0.3M, FY2015 $0.2M, FY2016 $0.4M, FY2017 $0.5M, FY2018 $0.4M, FY2019 $0.8M, FY2020 $1.3M, FY2021 $1.1M, FY2022 $2.4M, FY2023 $1.4M, FY2024 $1.2M approved, FY2025 $2.8M approved, FY2026 $5.6M. FY2024 and FY2025 are loans approved; every other year is capital deployed.
FY2024 and FY2025 are loans approved, as published in those years' annual reports. Every other year is capital deployed.
Who we finance
At least 3 of GAC's active clients are veteran-owned. Client figures as of June 30, 2026.
The median borrower credit score is 653. Most banks start declining around 680.
45%of respondents say their credit score rose because of the loan.
Credit score scale from 300 to 850.Median653680: most banks start declining
57% of borrowers with reported credit data had a score under 680.
The average borrower credit score is 671.
26% of respondents feel more confident approaching a traditional bank since borrowing from GAC.
60%Had funded their business from personal savings before coming to GAC
Many GAC borrowers are one crisis away from closing. Fewer than half, 47%, report having any business emergency savings.
67% could cover personal expenses for a stretch without new income.
40%Were able to hire, retain or add contractors after GAC loan
Small sample, so treat it as directional. But it's the most careful hiring claim we can make, because it asks borrowers to attribute the decision to the financing rather than just counting heads afterward.
4.47People employed per GAC business, on average
One business reporting 74 employees is left out as an outlier.
About these figures: Borrower survey, self-reported.
More than a lender
GAC combines character-based lending with hands-on technical assistance for underrepresented entrepreneurs on Chicago's South and West Sides. Every loan comes with coaching, financial education, and hands-on support, so businesses have what they need to start, grow, and build lasting wealth in their neighborhoods. Beyond capital, here's how we supported our borrowers this year:
GAC's technical assistance runs through four channels: one-to-one advising, mentorship for 30 businesses through Polsky, partner-hosted events, and the Owners Table.
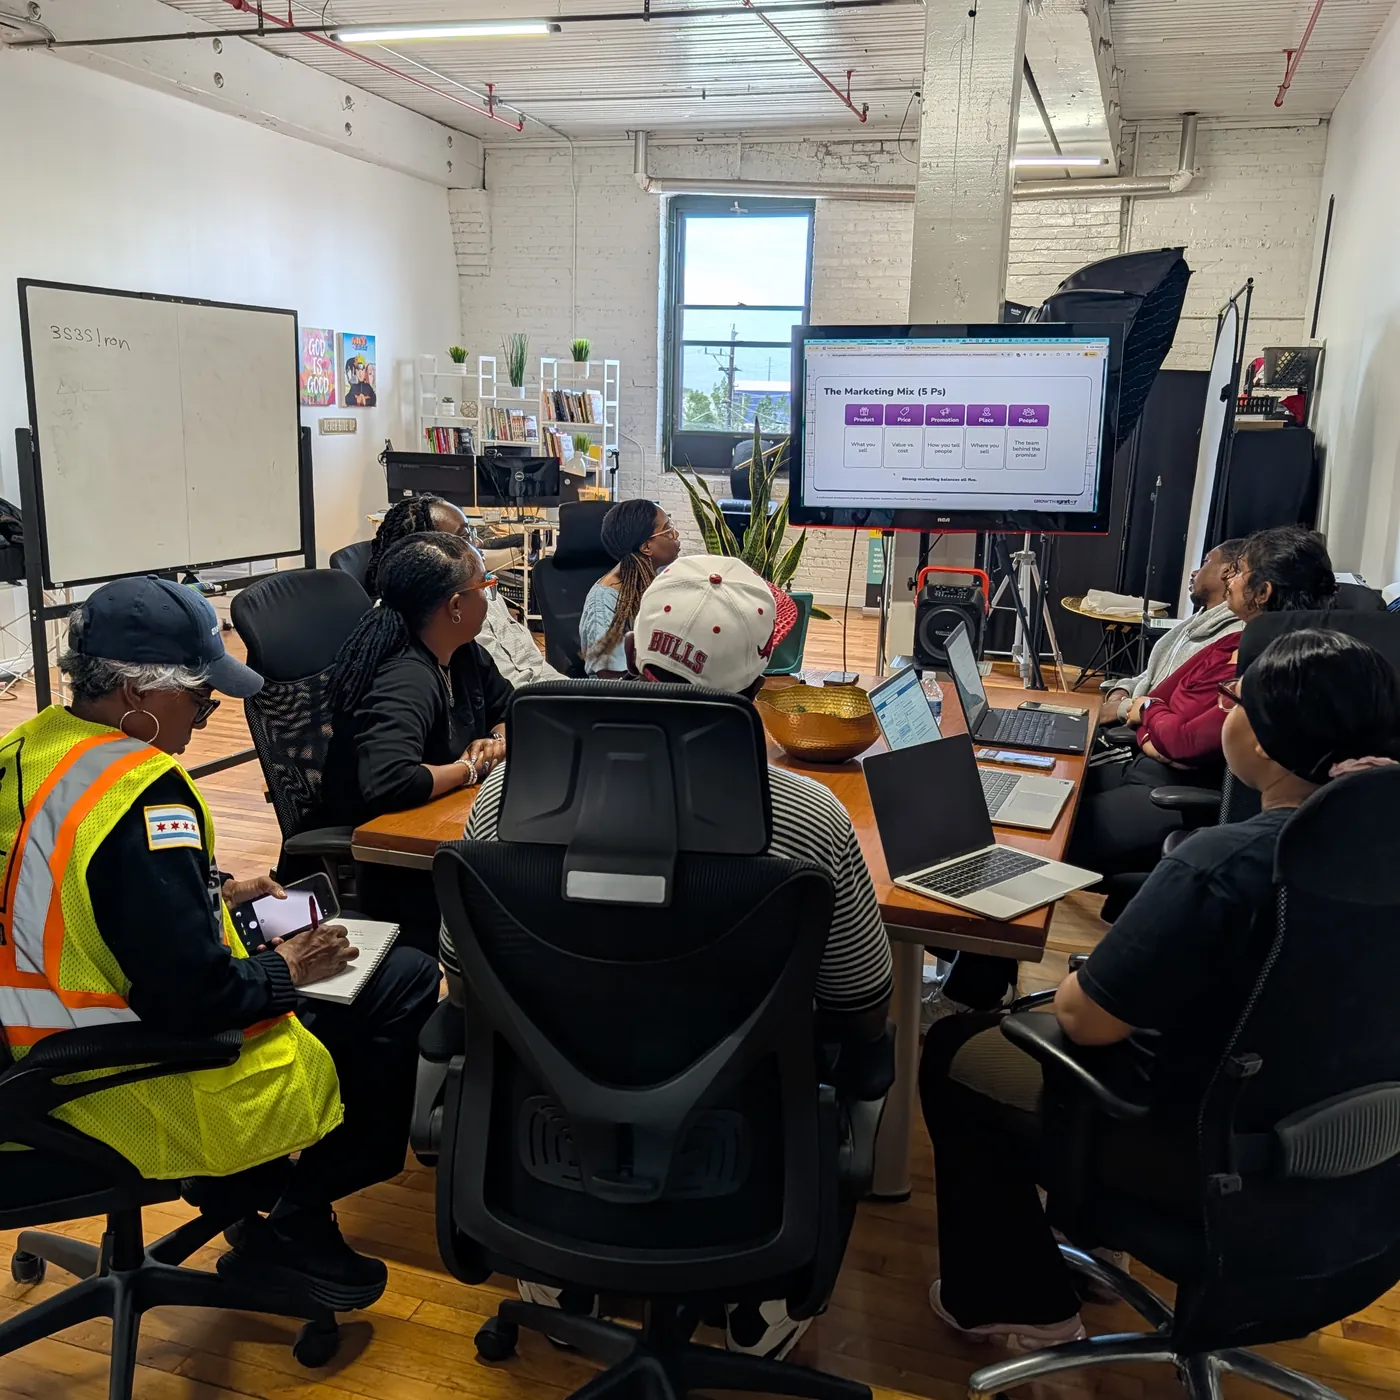
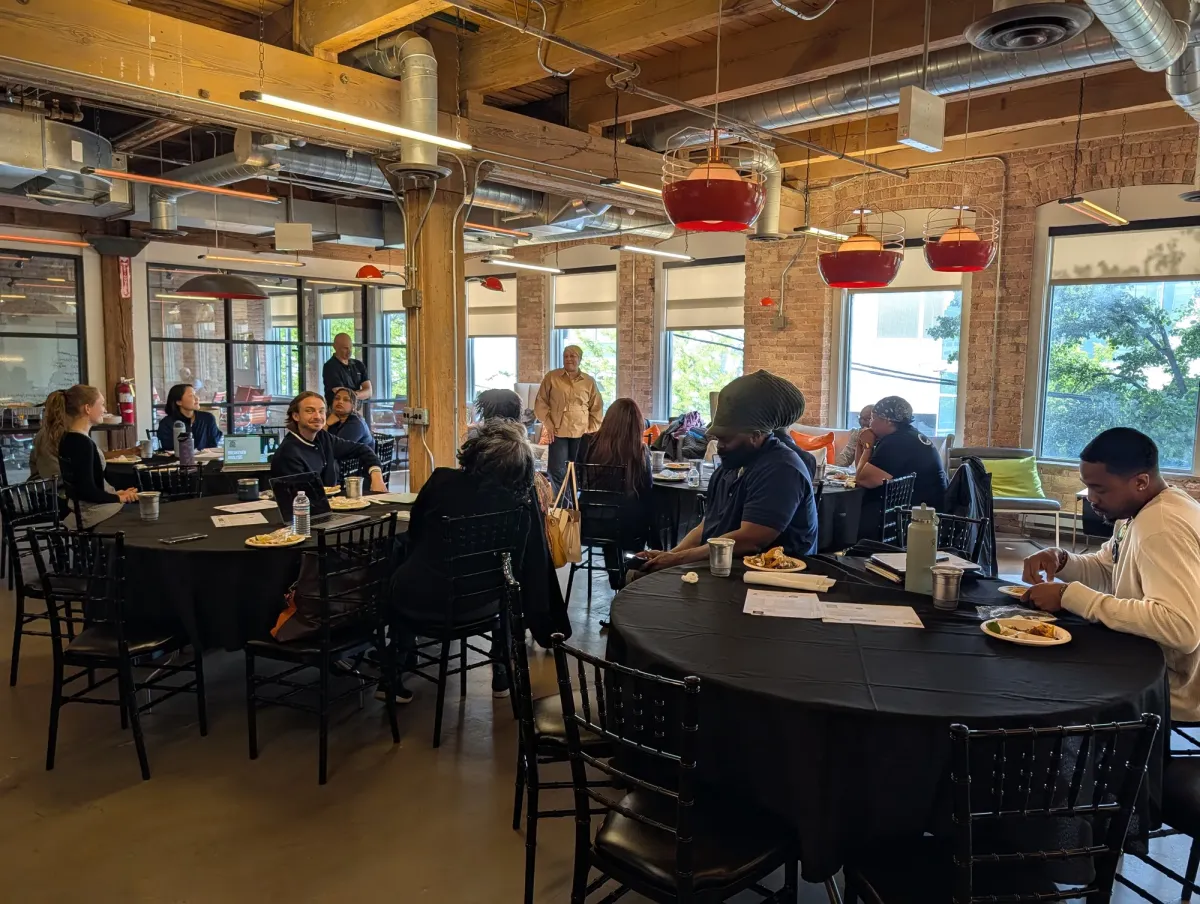
Monthly three-hour workshops, often held right at a borrower's shop, restaurant, or workspace, where entrepreneurs build relationships with each other, learn practical skills like cash flow management, pricing, and credit readiness, and network with bank partners and other business leaders who can help them grow. Sessions are open to the broader community, not just active borrowers, giving entrepreneurs a chance to connect with banks they may be ready to work with later.
A GAC technical assistance workshop
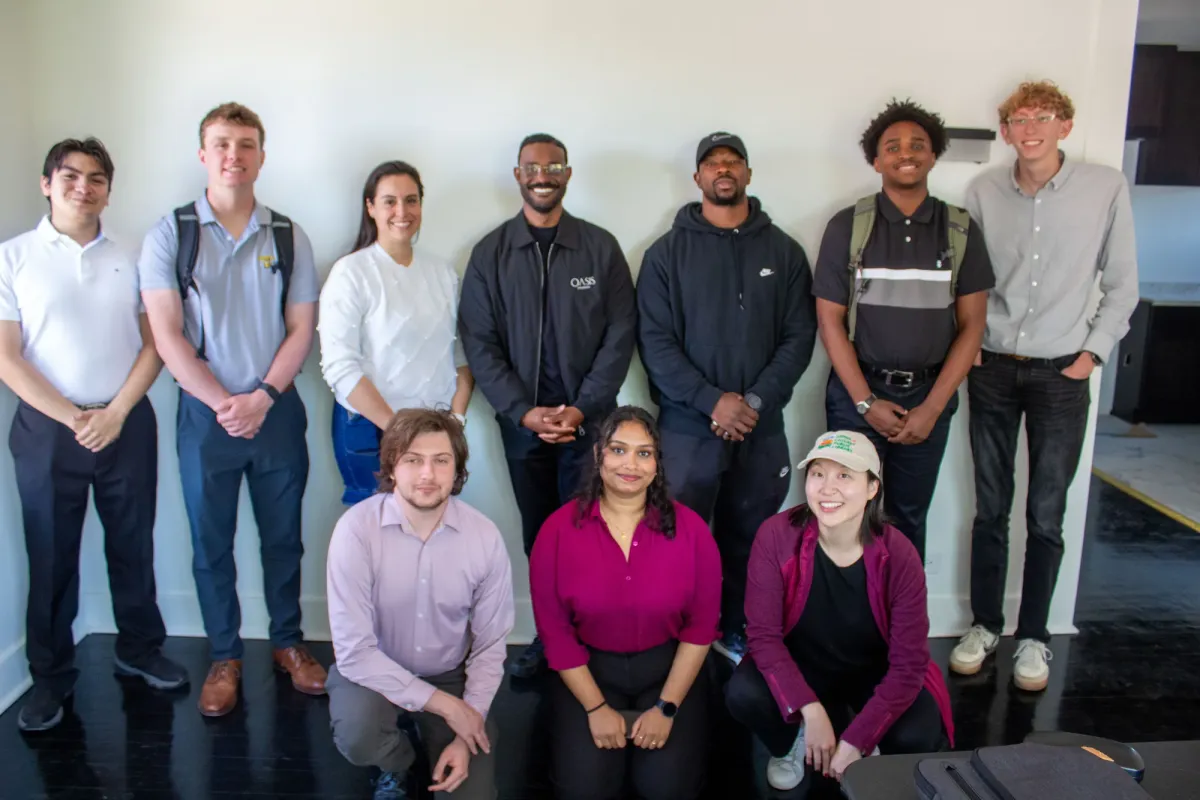
Marketing pilot interns
Back-office support
Many GAC borrowers have the drive, and now the capital, but not the expertise or bandwidth to put every good idea into practice. This year GAC launched its back-office pilot, starting with marketing.
Marketing pilot. GAC piloted a marketing program this year with a youth workforce partner, the Illinois Youth Investment Program, which funded five paid interns. GAC paired each intern with one small business, giving five businesses and ten youth participants the opportunity to go through roughly five sessions of marketing coaching. Each intern put in about 120 hours per business, which included building a Google Business Profile, writing website copy, taking photos, setting up Instagram and Facebook accounts, and creating three months of ready-to-post social media material.
Marketing support is one of the things borrowers ask for most, since good marketing expertise is expensive and hard to find. With funding, GAC wants to keep offering it on an ongoing basis and expand this model to include additional back-office support like bookkeeping and other financial services.
Industries financed
Chicago's small businesses face a gap in access to capital, which is where GAC steps in to support.
FY2026 businesses financed, by industry
FY2026 businesses financed, by industry, out of 42: Food and Beverage 17 (40%), Construction and Trade Services 7 (17%), Retail 4 (10%), Professional and Business Services 4 (9%), Personal Services 3 (7%), Education and Child Care 2 (5%), Manufacturing and Production 2 (5%), Transportation and Logistics 2 (5%), and Creative, Media and Entertainment 1 (2%).
Food & Beverage1740%
Construction & Trade Services717%
Retail410%
Professional & Business Services49%
Personal Services37%
Education & Child Care25%
Manufacturing & Production25%
Transportation & Logistics25%
Creative, Media & Entertainment12%
Number of businesses in each sector, and its share of the 42 financed in FY2026.
Survival is drawn from GAC's loan records. The other three are self-reported in the 2026 borrower survey.
Annual revenue, drawn to scale
Stories from GAC-supported entrepreneurs
GAC finances and supports business owners across Chicago's South and West Sides. Five of them tell their stories here.
Greater Grand Crossing
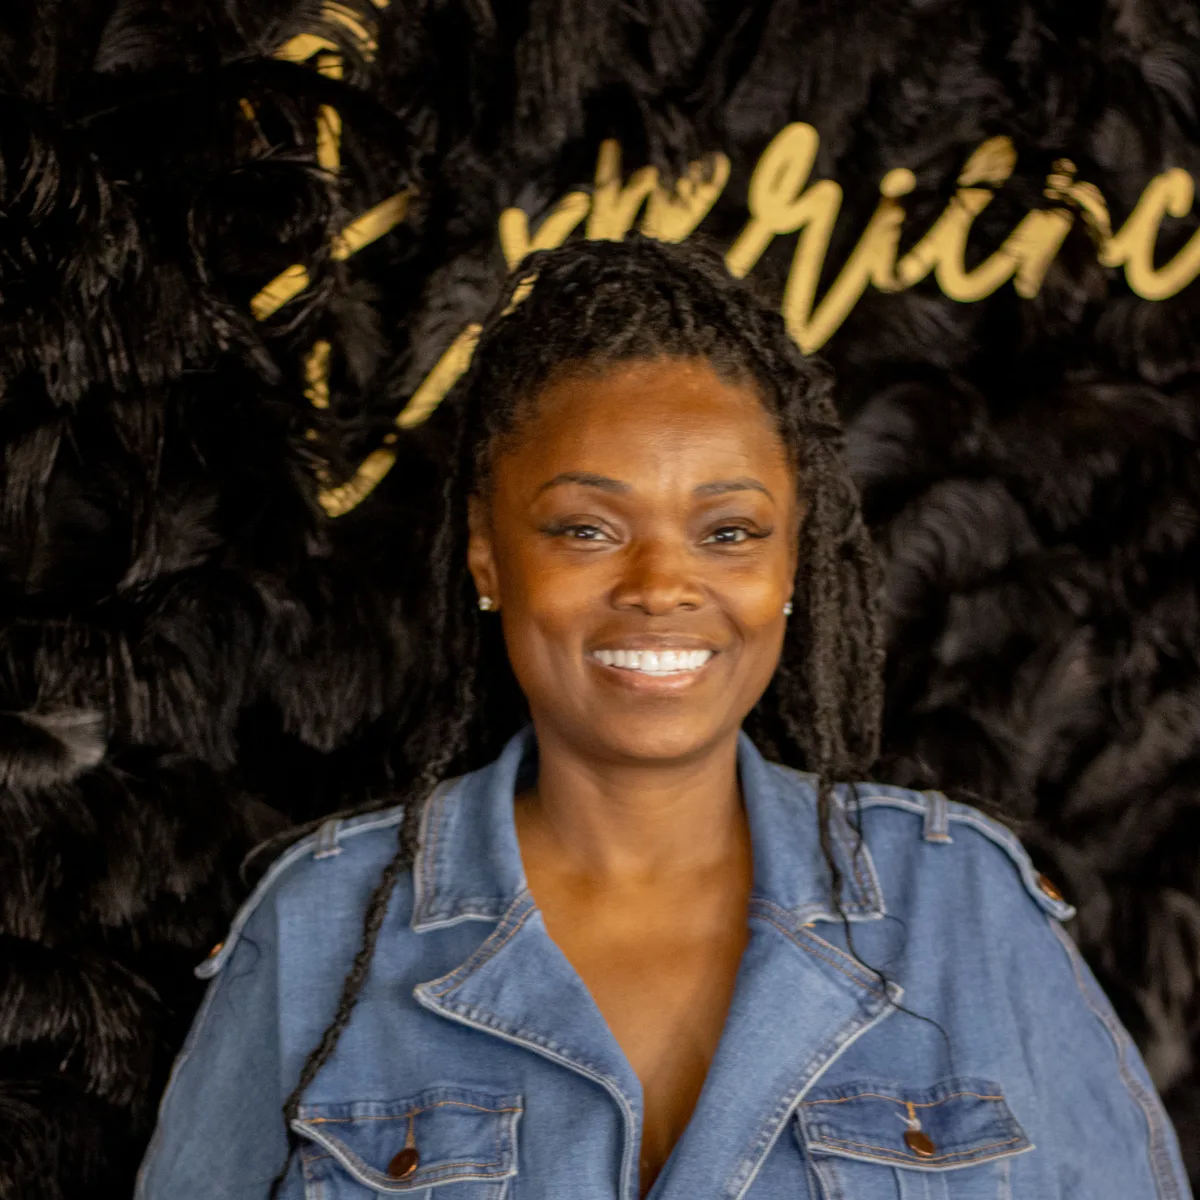
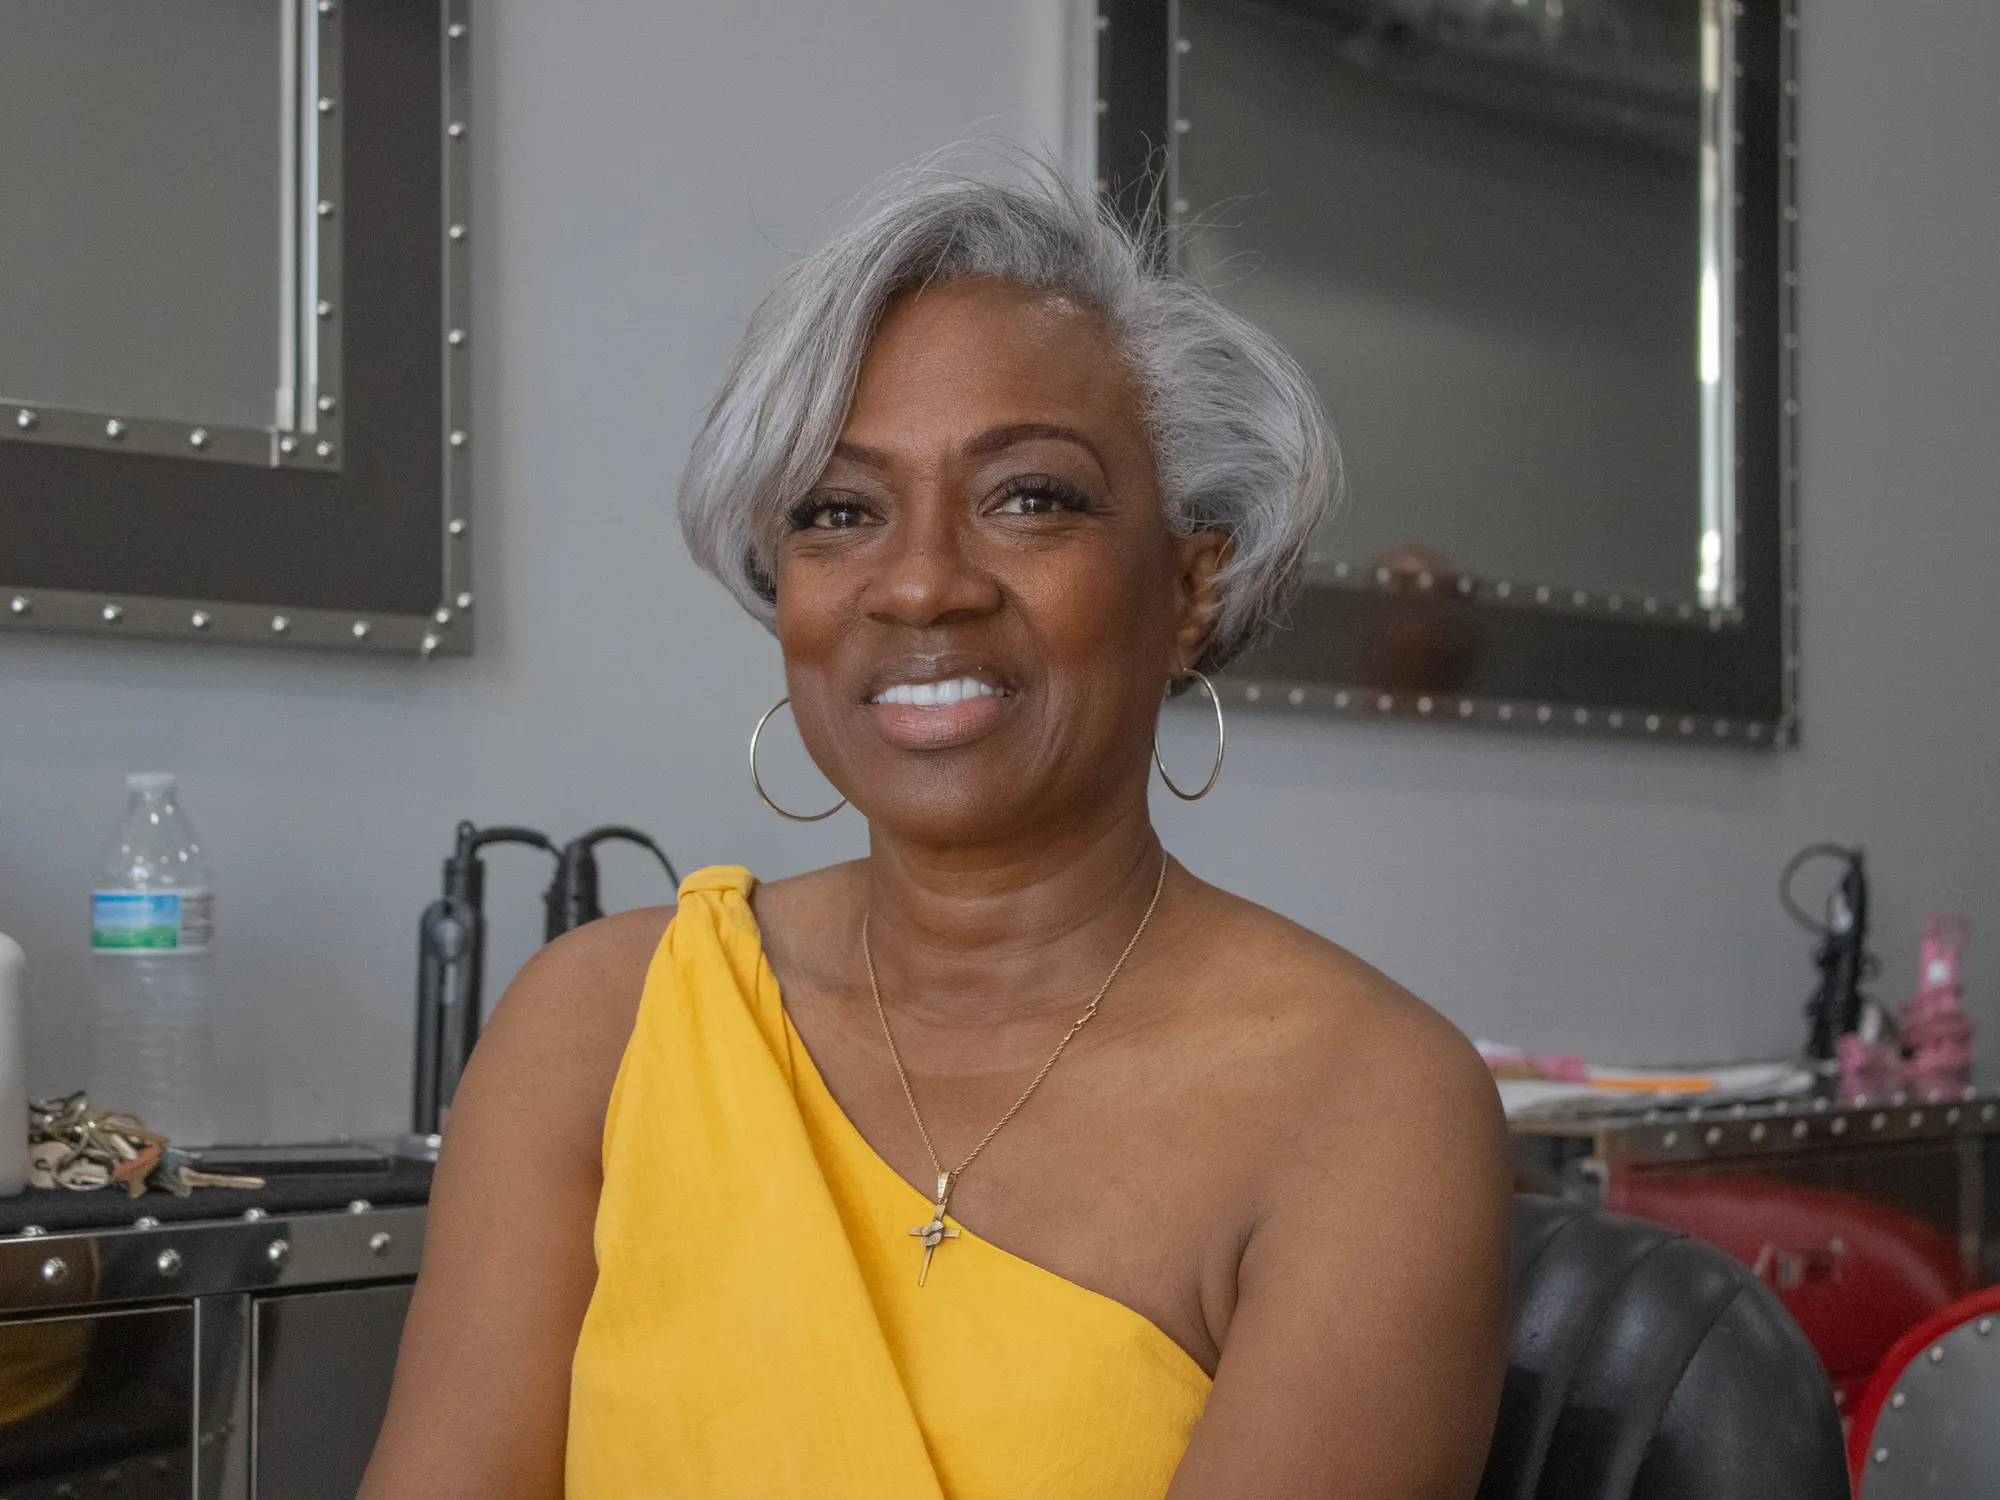
Patrice Bailey-Waugh
Patrice's Picture of Beauty
“GAC helped save my business at a very critical time.”
Personal Services
GAC instrument: Bridge
Avalon Park
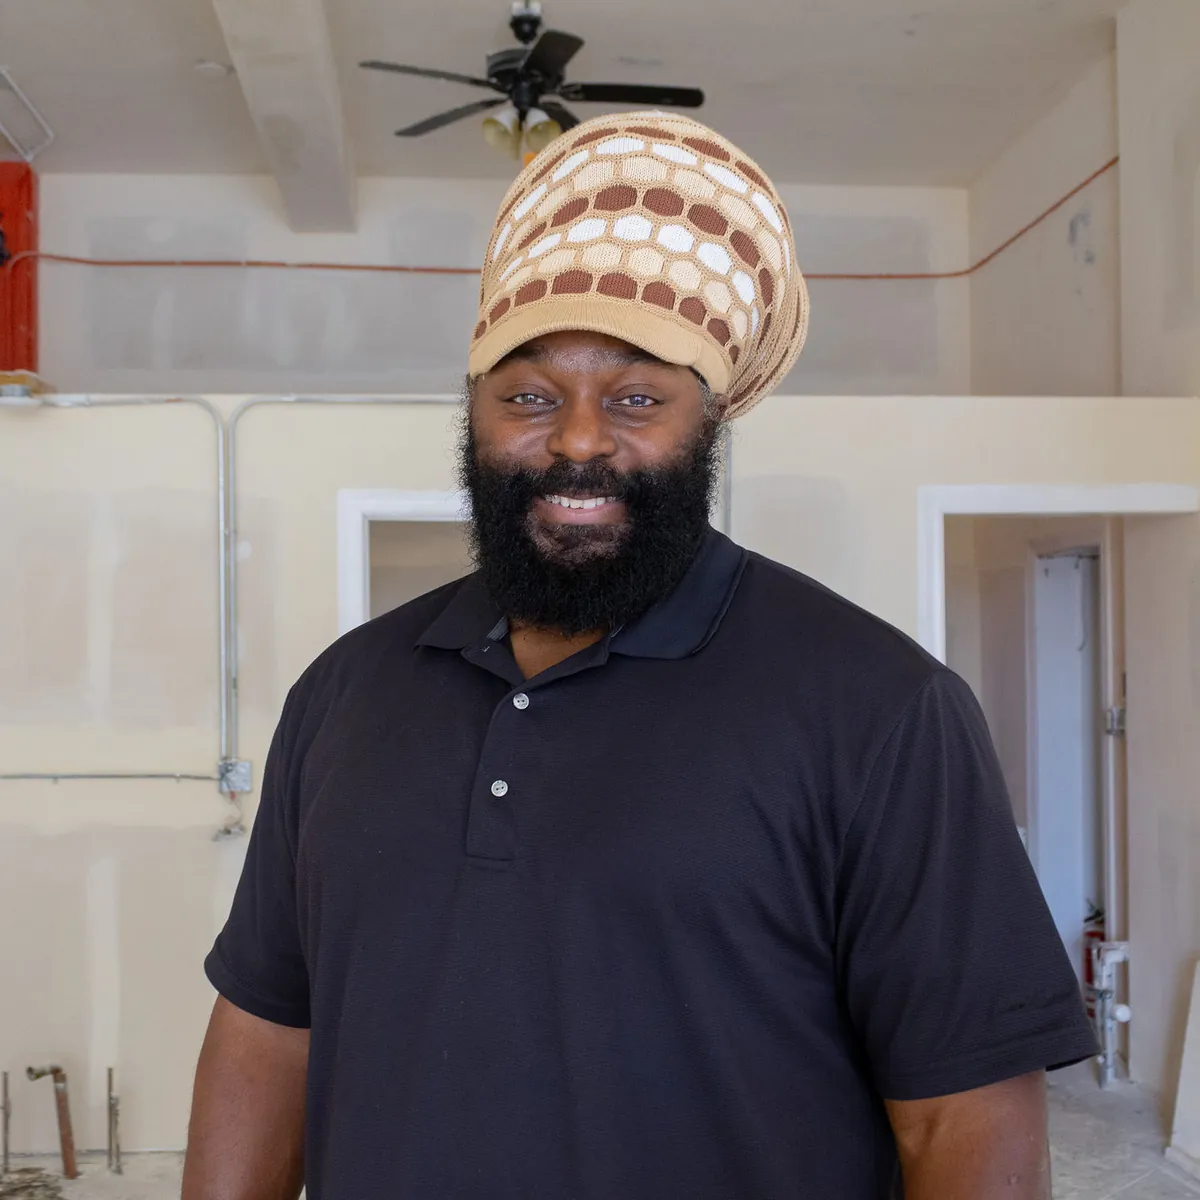
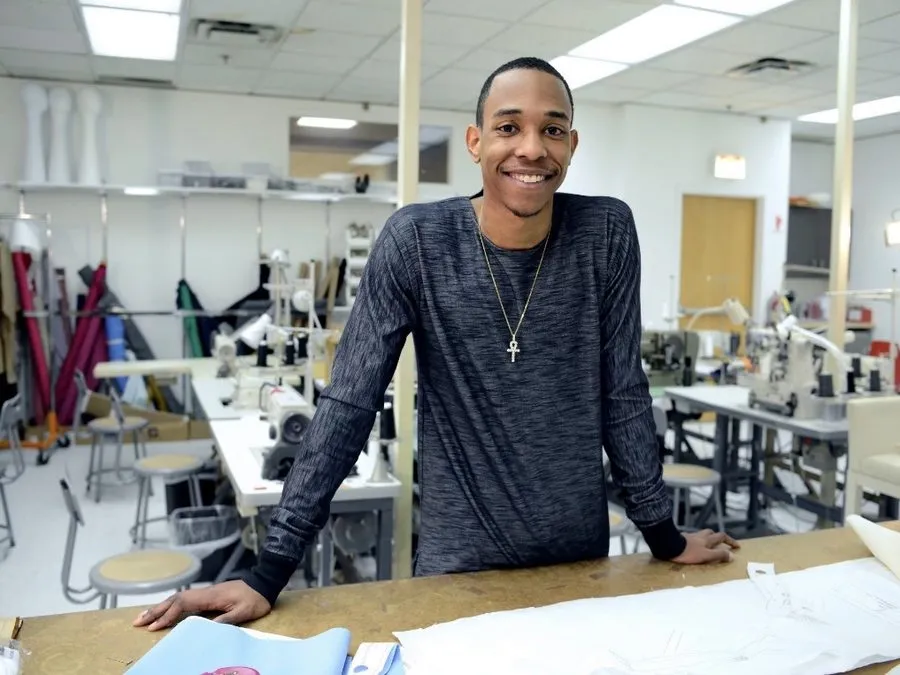
Dondre Smith
ALMVGHTY Clothing & CRE8 Space
“That micro equity fund loan allowed us to get back in the game.”
Apparel & Manufacturing
GAC instrument: CMEF
Auburn Gresham
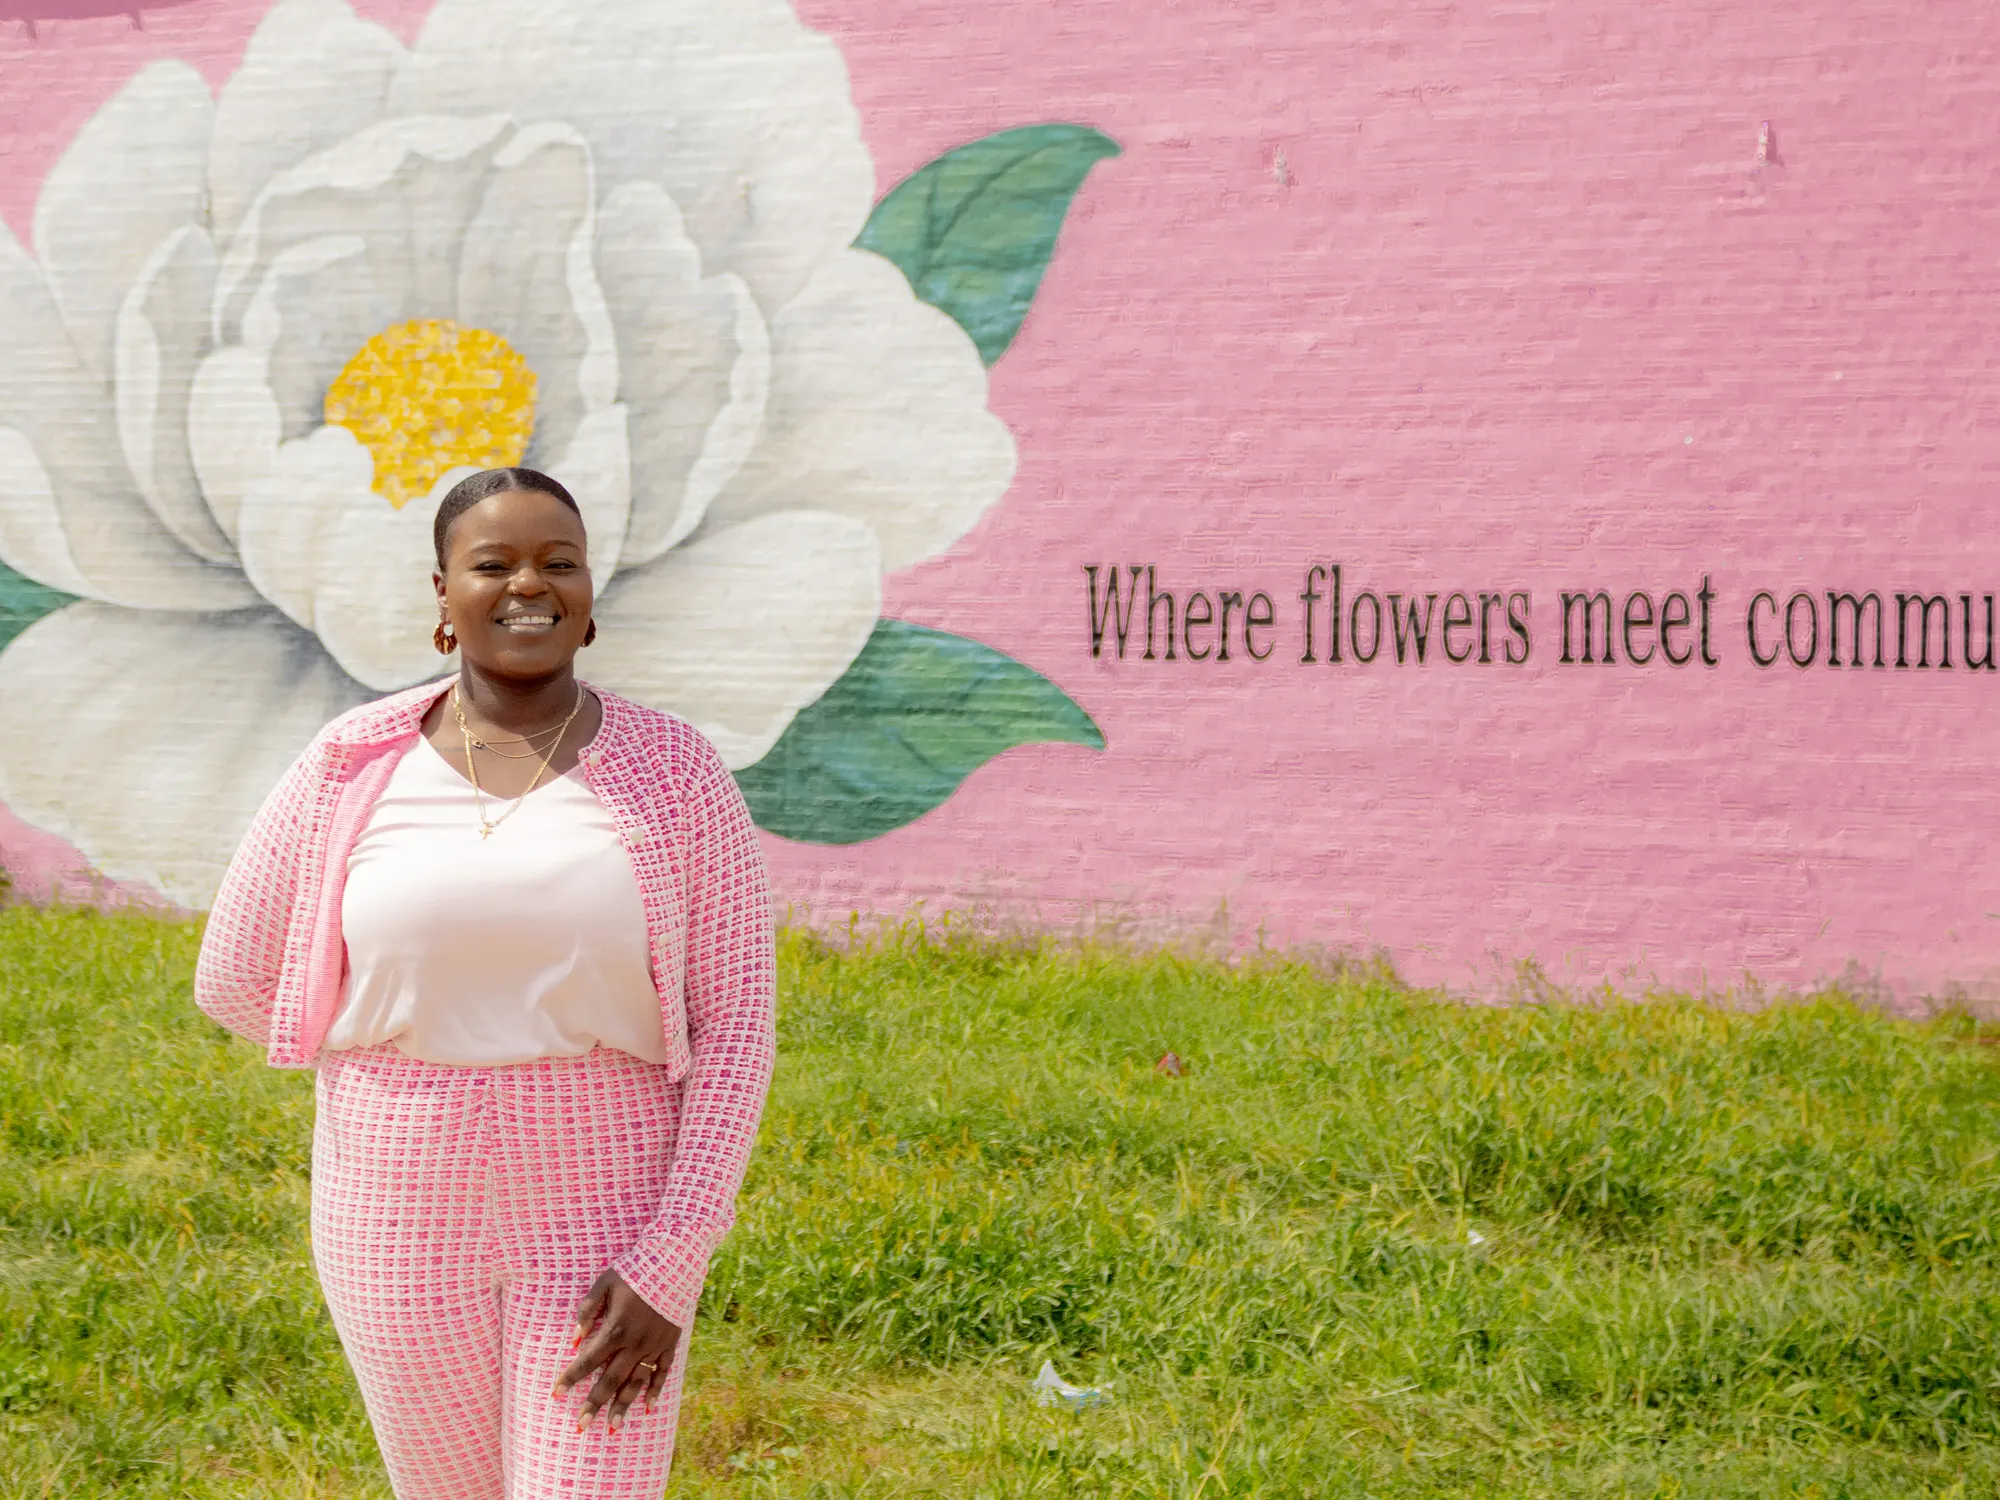
Tatiana Williams
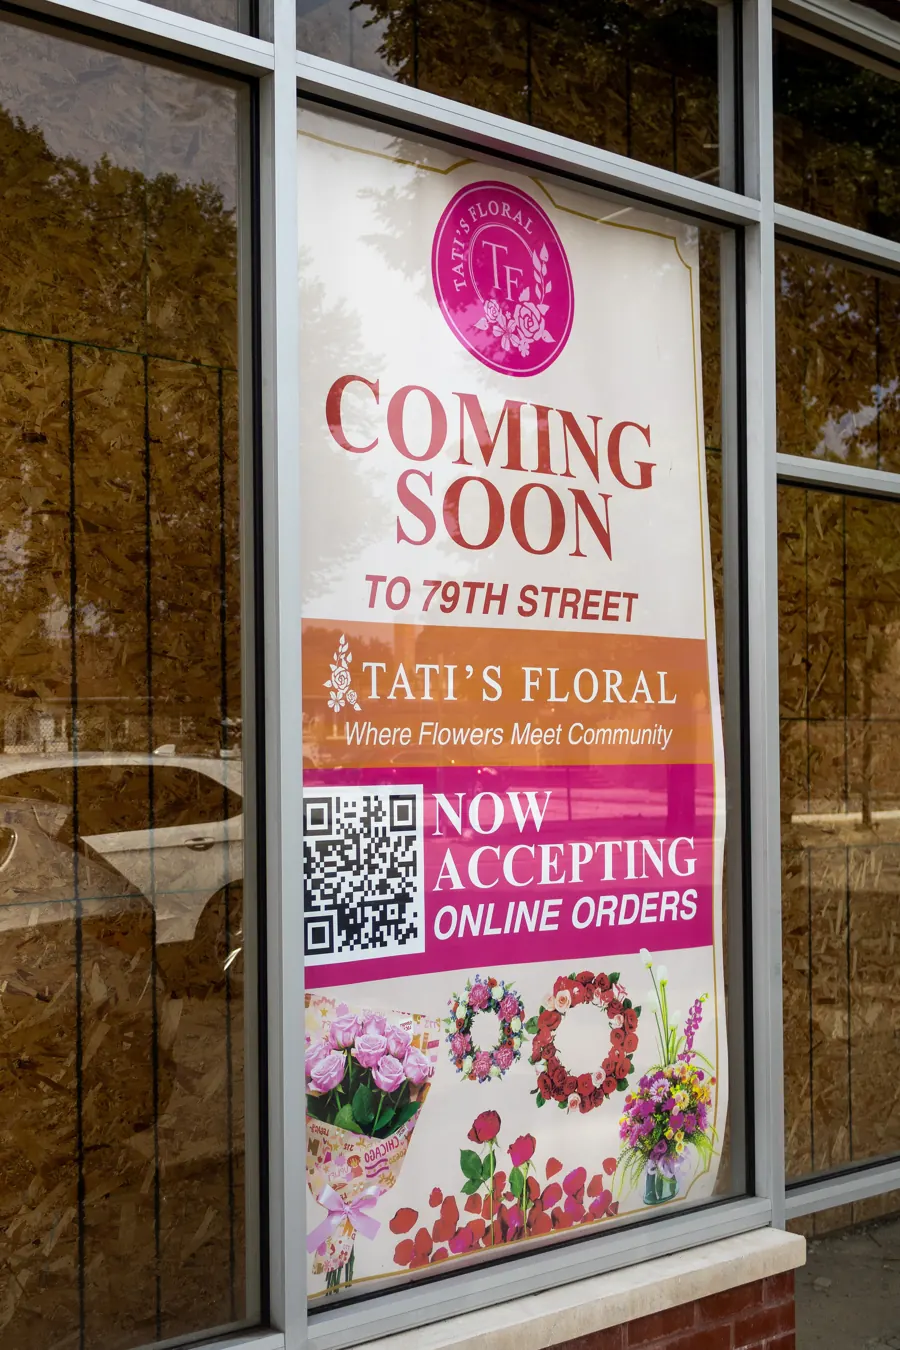
Tati's Floral and Suites
“You can never go wrong with a flower.”
Retail & Floral
GAC instrument: Bridge
South Shore
Luster Lockhart
Jeffery Java & Juice
“GAC's financing has allowed Jeffery Java to build out the space.”
Food & Beverage
GAC instrument: Bridge
Austin
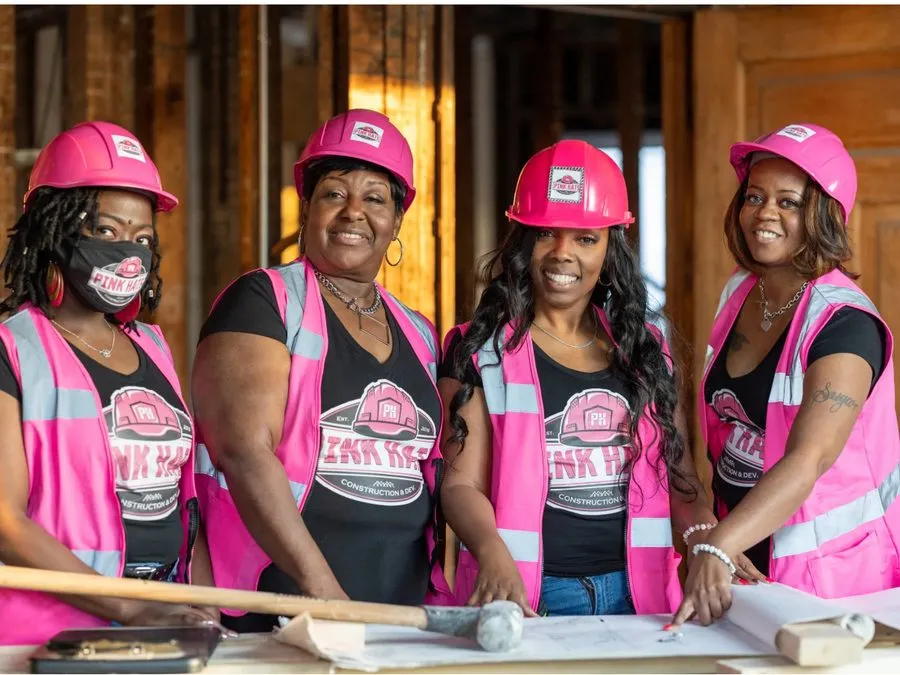
Traci Quinn
Pink Hats Construction & Development Group
“Believing in an entrepreneur means looking beyond a spreadsheet.”
Construction & Trade Services
GAC instrument: Working capital
Rebuild 2.0
A loan builds a business. Here it builds a house.
Rebuild 2.0 shows how GAC connects capital with the right partners and borrowers to support the Chicago area's entrepreneurial ecosystem.
Builders Avenue works alongside GAC on these projects, handling pre-construction, estimating, legal representation, and the back-end work a contractor needs before a project can even start. Once that groundwork is laid, GAC supports a growing contractor by building financial literacy and providing operating capital and lines of credit.
Two of those contractors tell the story in their own words.
How Rebuild 2.0 works
City of ChicagoRuns the Rebuild 2.0 initiative
A $5 million fundGAC administers it, one of three CDFIs
The contractorA GAC borrower builds, and GAC lends on the construction side
Homes in Pullman and RoselandVacant homes become accessible for-sale housing
The openingCatered by GAC clients
Capital stays in the neighborhood
Rebuild 2.0 project photo, Roseland
Roseland
Luis Castro
USA Roofing
“GAC visits the projects in person. That shows the borrower they truly believe in you and want you to succeed.”
Construction
Operating capital and lines of credit
Renovation under way, Roseland
Roseland
Jimmy Williams
Certified Property Solutions
“They were not judging me on a credit score or a past. They were looking at the present, the future of the business, and most of all my character.”
Construction
Working capital
The opening
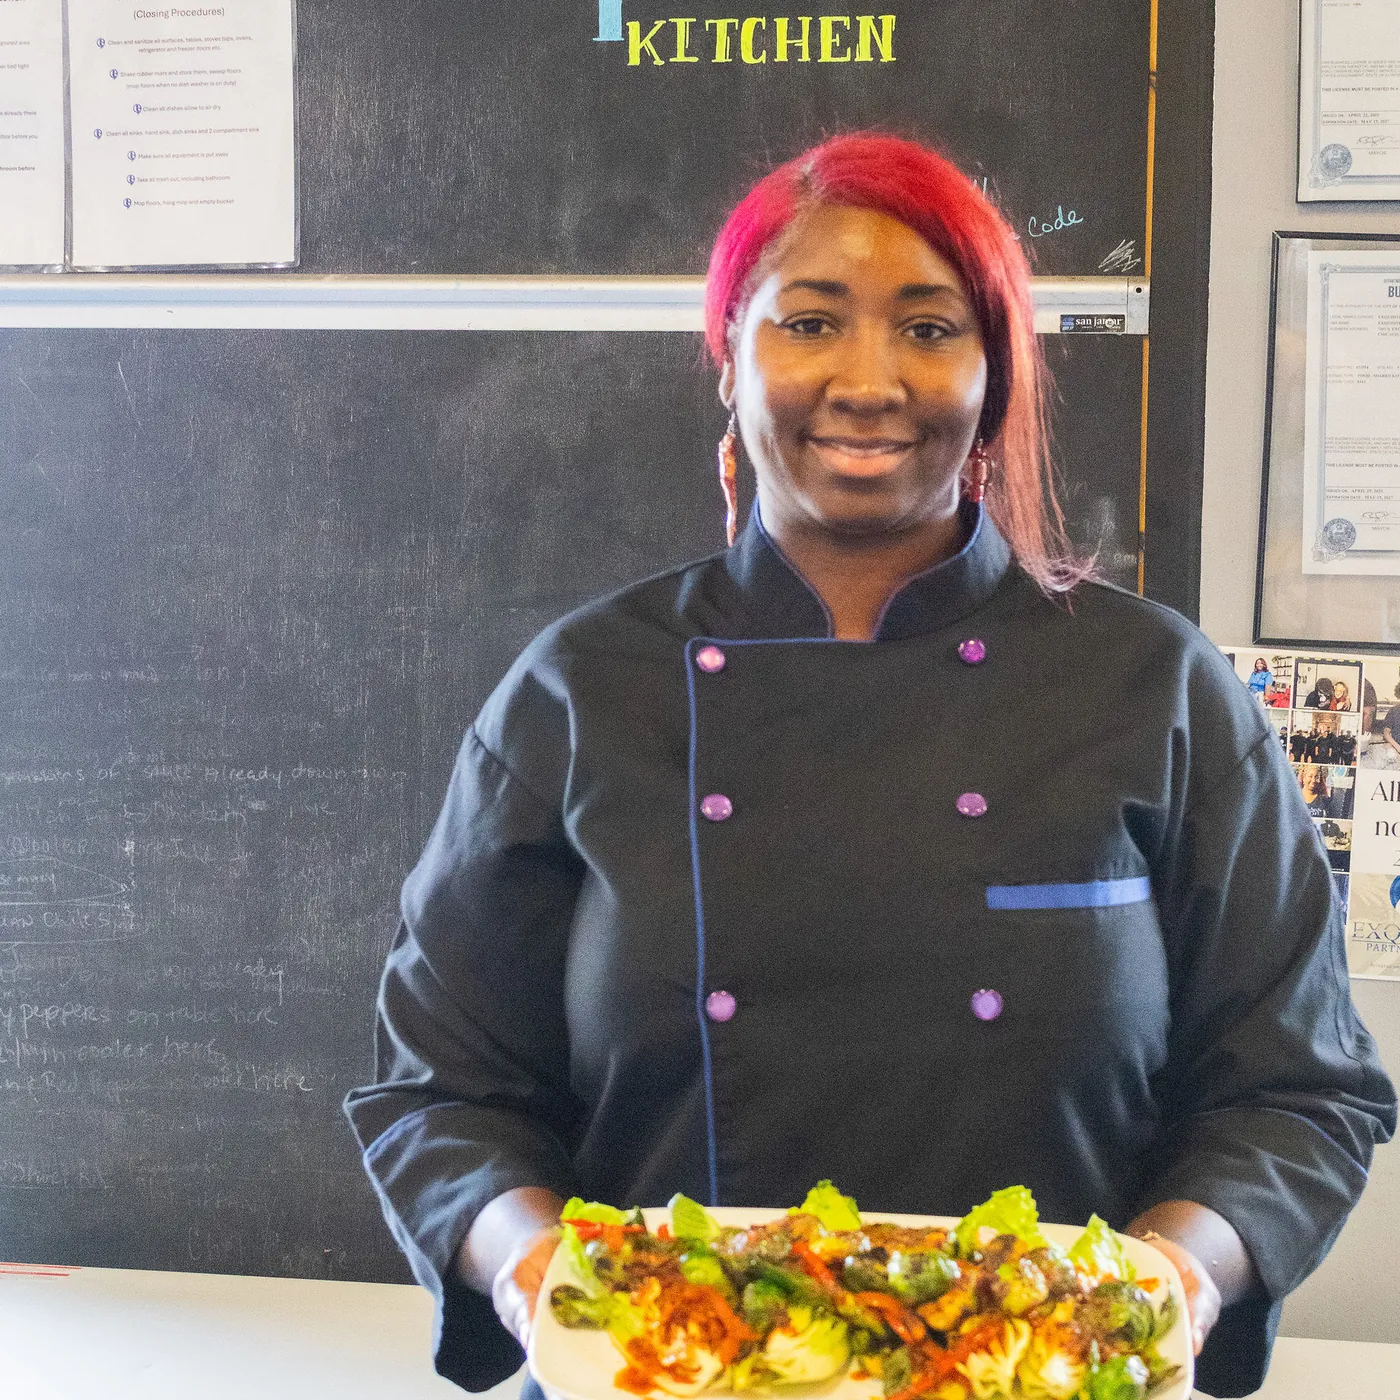
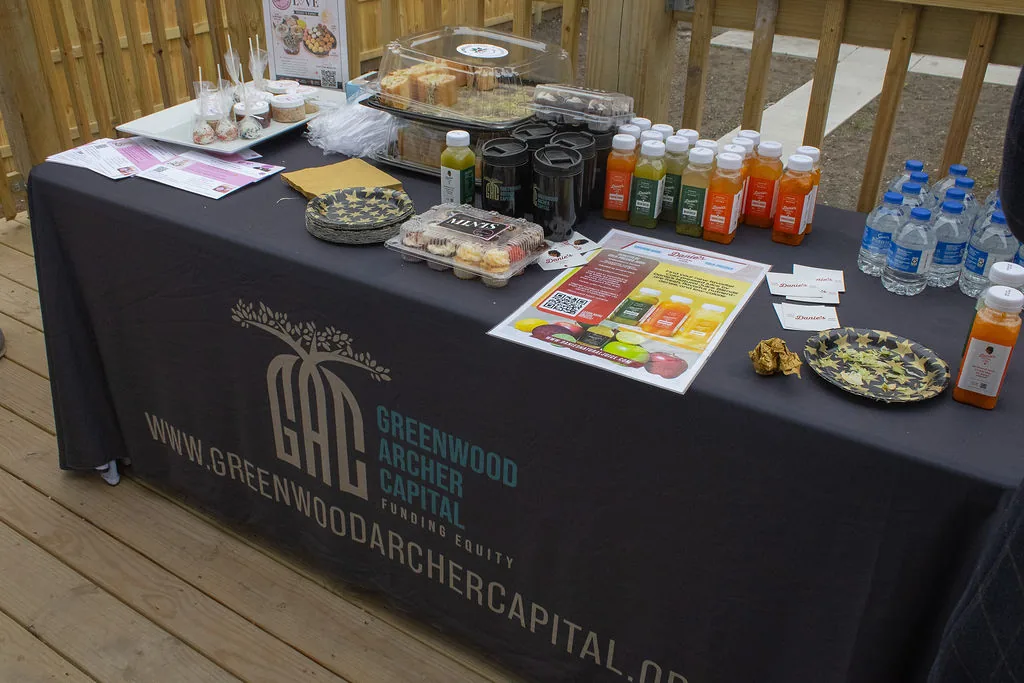
GAC's commitment to its borrowers shows throughout the Rebuild 2.0 project, including during the opening. When a ribbon-cutting needed refreshments, GAC hired its own clients to cater it. Our dedicated team is always looking for opportunities to showcase our clients' talent and to hire from our borrower pool to keep showing up for our businesses. From the capital behind it, to the contractors who built it, to the borrowers who catered its opening, Rebuild 2.0 is an example of GAC's holistic approach in one project.
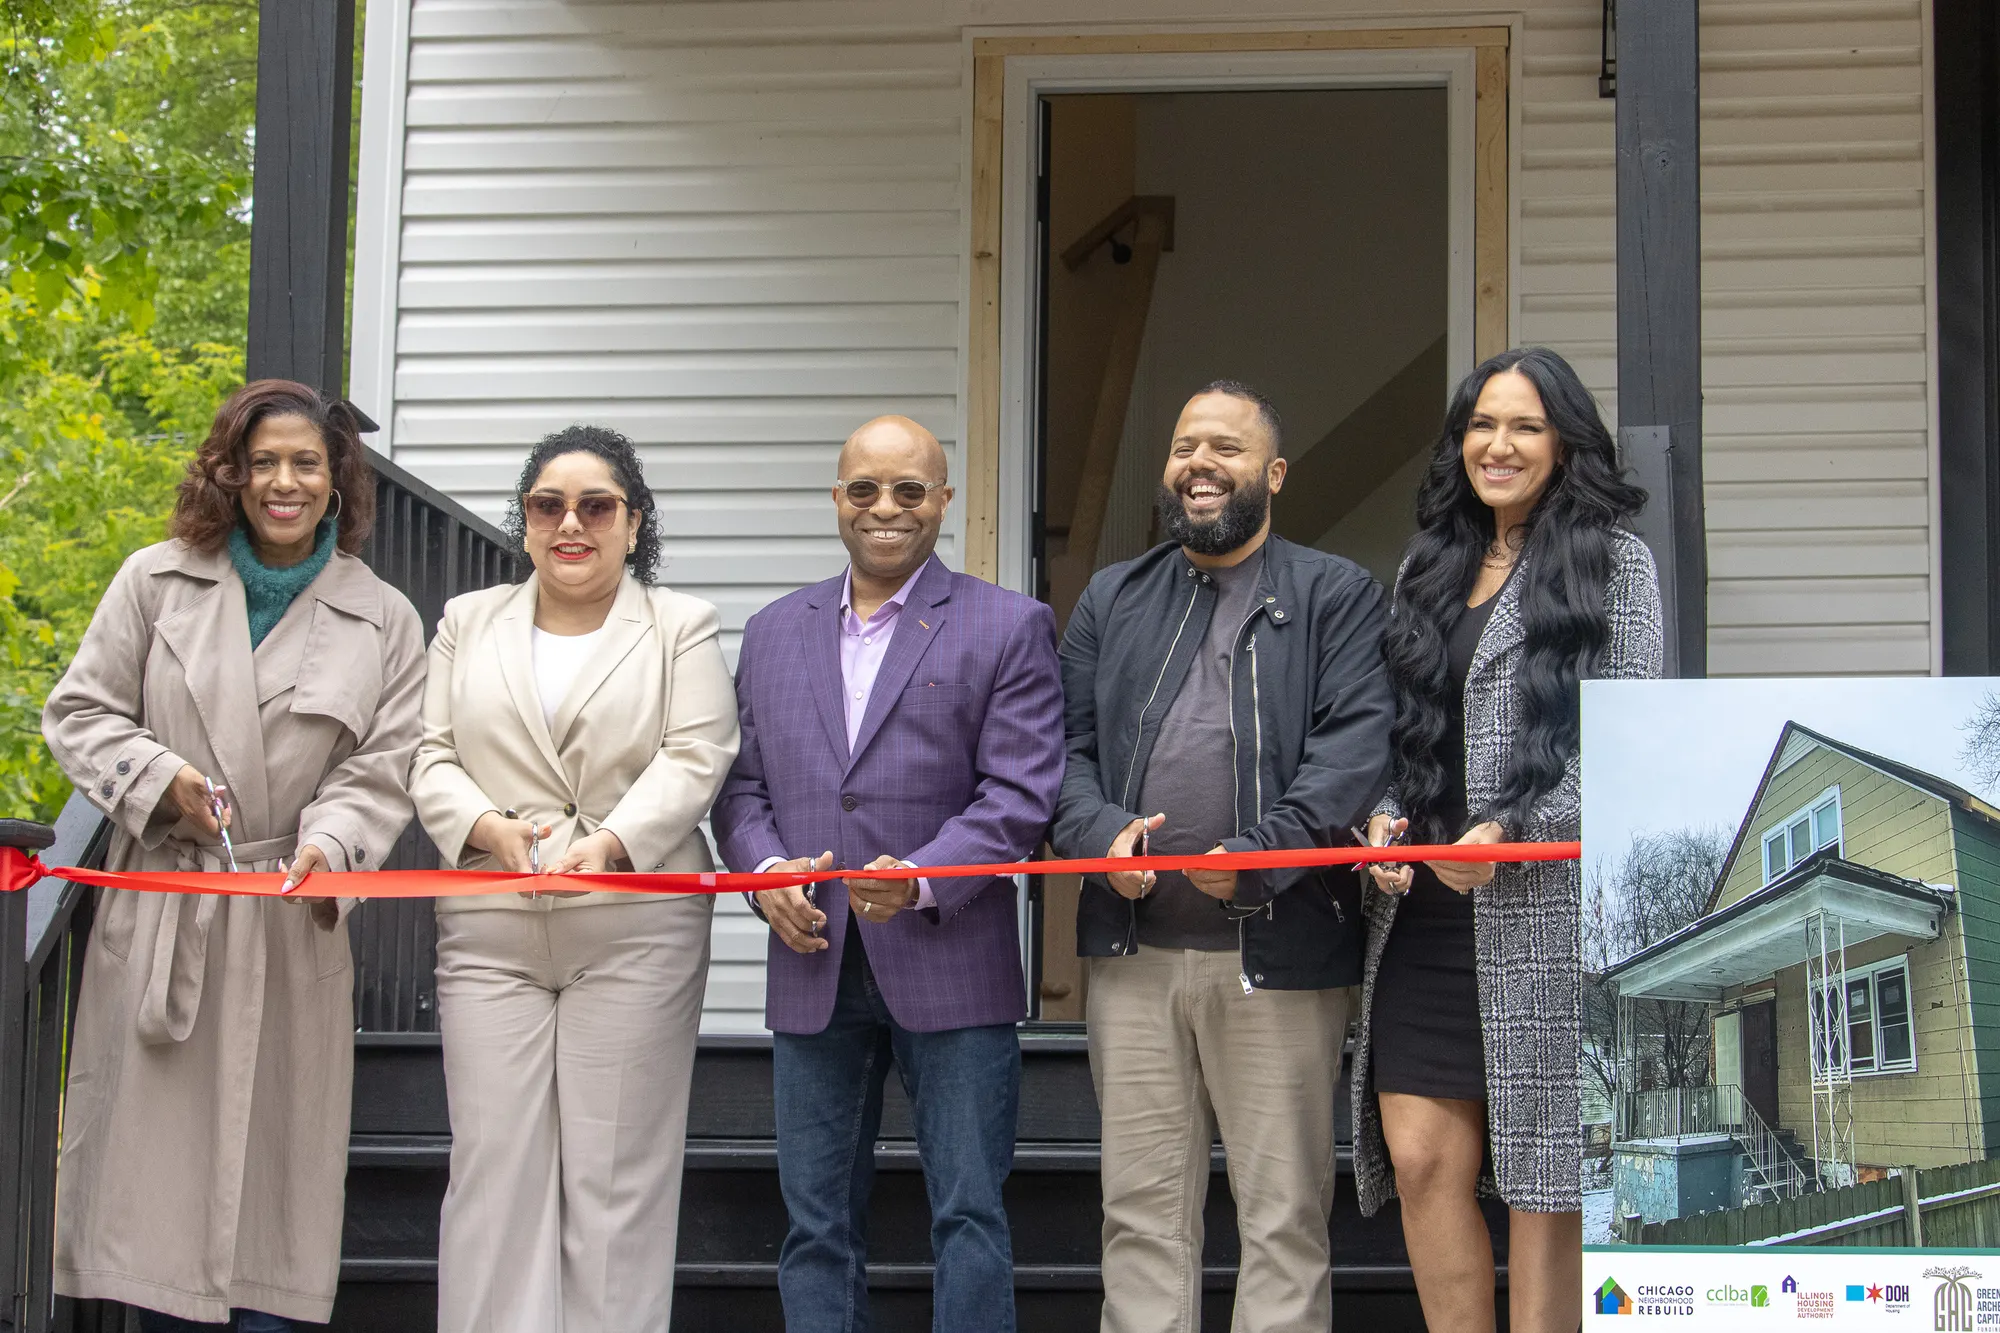
Ribbon-cutting at a completed Rebuild 2.0 home, Roseland
Ribbon-cutting at a completed Rebuild 2.0 home, Roseland
Work underway on a Rebuild 2.0 property, Roseland
Renovation under way, Roseland
Where GAC is lending
Use this interactive map to explore GAC's 103 active clients, filterable by industry, community area or ownership. Client counts, community areas and the map are as of June 30, 2026, the close of FY2026. Each pin sits in its client's community area, or its town outside Chicago, not at an address.
Map could not load. The client list is below.
Showing 103 clients
Client list
Clients matching the filters, by business, industry and place
Business
Industry
Where
Five of the six community areas with the most GAC clients are on the South Side.
How GAC's work lines up with the City's Build Better Together pillars
Growth of quality housingGAC borrowers are building the Rebuild 2.0 homes in Roseland. How the fund works: Rebuild 2.0, in Stories.
Growth of jobs and business innovation$5.6 million deployed to 42 businesses in FY2026.161 people employed across 36 surveyed businesses (borrower survey).
Growth in vibrant cultural neighborhoodsGAC clients operate in 32 of Chicago's 77 community areas.In FY2027, GAC will focus lending along specific commercial corridors.
Pillars from the City of Chicago's Build Better Together strategy. The comparison is GAC's own.
Support our growth
GAC intends to lend more next year, and to more businesses. Growth means going deeper into the corridors where we already work rather than spreading across the city, so that each new loan lands on a street where GAC already has borrowers.
That depends on partners. Here is where it would make the most difference.
FY2024$1.2M
FY2025$2.8M
FY2026$5.6M
FY2027
FY2027Continue to invest in character-based lending
We will keep lending the way we always have, person-first and character-based, centered on trust, relationships, and lived experience rather than a credit score alone.
FY2027Build out back-office support
After this year's marketing pilot, we want to add bookkeeping and other financial services for borrowers.
FY2027Focus lending along specific commercial corridors
We will target lending to revitalize corridors in historically disinvested communities.
Ways to support us
A grantThe strongest dollar GAC has, because it never has to be repaid. It becomes lending capital that goes out, comes back, and goes out again. Fund GAC once and you fund every loan after it.
A loan at low interestLend GAC capital below market and GAC lends it on. Your money is still yours and still comes back. It just works a South or West Side block first.
Fund a TA sessionPay for the bookkeeping, pricing and credit work GAC does alongside the loan. It is what makes the loan repayable, and what keeps the business open once it is repaid.
First-loss capitalCover the first losses in a pool and GAC can say yes to borrowers whose numbers are thin but whose plan and character are sound. It buys GAC room to lend on judgment.
Build a program with usPick a corridor or a sector and fund it with GAC end to end, the lending and the people who run it. You set the target, GAC does the work on the ground.
Partner with GAC
Every loan GAC makes rests on partners who believe in the entrepreneurs of Chicago's South and West Sides. If your institution lends, invests, or gives, we would welcome the chance to talk about what we can build together.
None of this happens without the partners and funders who trust us with their capital, and the borrowers who trust us with their businesses. Thank you for standing with GAC this year. As we look toward FY2027 and the work ahead, we're grateful for that support and ready to keep earning it.